

BusinessesPolicies processed980 Claims Processed245 Nº Clients720
Property damage insurance
In the business world, unforeseen events can arise at any time, transcending sectoral boundaries. In this context, the need to protect against these risks becomes crucial.

In short
What is property damage insurance
Property damage insurance covers the company's physical assets —building, machinery, stock, and facilities— against fire, water, theft, weather events, and breakdown. Its essential complement is business interruption, which compensates for the margin the company fails to earn while it cannot produce. Without this second cover, a company can rebuild its premises and still close due to lack of cash flow during the downtime.
Advantages
Advantages of property damage insurance
Asset cover protects the balance sheet; profit cover ensures the company continues to exist.
Cash flow does not stop with production
Loss of profits pays salaries, rents, and financing while no invoicing occurs. It is the difference between a hard stop and a definitive closure.
Rebuild without decapitalising
Compensation at replacement value avoids having to finance the difference with expensive debt just when the bank sees you as a high risk.
Better premium for investing in protection
Sprinklers, detection, and compartmentalisation translate into premium reduction year after year. The investment in safety also pays off in this way.
Reassure your financiers
Financial entities and landlords require proof of sufficient cover on affected assets. A well-dimensioned programme unlocks investment operations.
Profile
Who we work for
Industry and manufacturing
Plants with critical machinery whose replacement has long lead times and no immediate alternative.
Logistics and warehousing
Warehouses with high value concentration in stock and seasonal stock variation.
Retail and distribution
Networks with multiple locations where the risk is dispersed but continuity depends on the logistics centre.
Corporate property
Property companies and landlords responsible for the building and loss of rental income.
Scope
Main covers of property damage insurance
- Fire, lightning, explosion, electrical damage and vandalism
- Water damage, atmospheric phenomena and natural risks
- Theft and robbery of stock, equipment and cash
- Machinery and electronic equipment breakdown, with all-risk option
- Loss of profits: gross margin, fixed expenses and indemnity period adjusted to the actual replacement time
- Debris removal, demolition, salvage and professional fees
The JORI method
How we work
Risk analysis
We study the activity, assets, and plausible scenarios. Without that diagnosis, comparing policies is comparing prices of different things.
Programme design
We define covers, limits, deductibles, and acceptable exclusions. We decide what is transferred to the insurer and what is consciously retained.
Negotiation with the market
We present the risk to the insurers we work with and negotiate terms. We are independent: we do not belong to any company.
Support and claims
We review the programme at each renewal and, when a claim occurs, we act as your technical representative with the insurer until payment is received.
Frequent doubts
Most frequently asked questions about property damage insurance
What is the proportional rule and how does it affect me?
If you insure for less than the real value, the insurer compensates in the same proportion. With a warehouse worth 2 M€ insured for 1 M€, a claim of 400,000 € is compensated with 200,000 €. This is why we review sums insured at each renewal.
How is the loss of profits calculated?
It starts with the annual gross margin (sales minus variable expenses) and sets an indemnity period that should cover the actual time to recover the previous level of activity, not just until reconstruction. In industries with imported machinery, twelve or eighteen months is usually prudent.
Is it worth hiring the prior valuation of sums insured?
For risks above one million euros, almost always. An agreed valuation with the insurer eliminates the discussion about underinsurance on the day of the claim, which is when the company has the least negotiating power.
What exactly does the Consorcio cover and what does the policy cover?
The Consorcio de Compensación de Seguros compensates extraordinary risks —extraordinary flood, earthquake, terrorism— as long as there is a policy in force and the surcharge has been paid. The rest of the causes are covered by your insurer. We coordinate both files to prevent them from referring to each other.
Can I insure at new value or only at real value?
It is possible to agree on replacement value as new, which is recommended for machinery and buildings. Without this agreement, compensation is at real value, deducting depreciation, and the company has to cover the difference out of pocket to replace.
What happens if I increase stock during the campaign?
A stock variation clause or an automatic margin on the average capital is contracted. It is an inexpensive modification that avoids underinsurance just at the moment of maximum exposure.
Property Damage
Let's talk about protecting your business
Insights
View the topic property risks What we have written about this
Analysis
Loss of profits: the indemnity period that almost no one calculates correctly
Twelve months is the market standard and a decision that is rarely reviewed. In many industries, it is not even enough to replace the critical machine.
7 min readAnalysis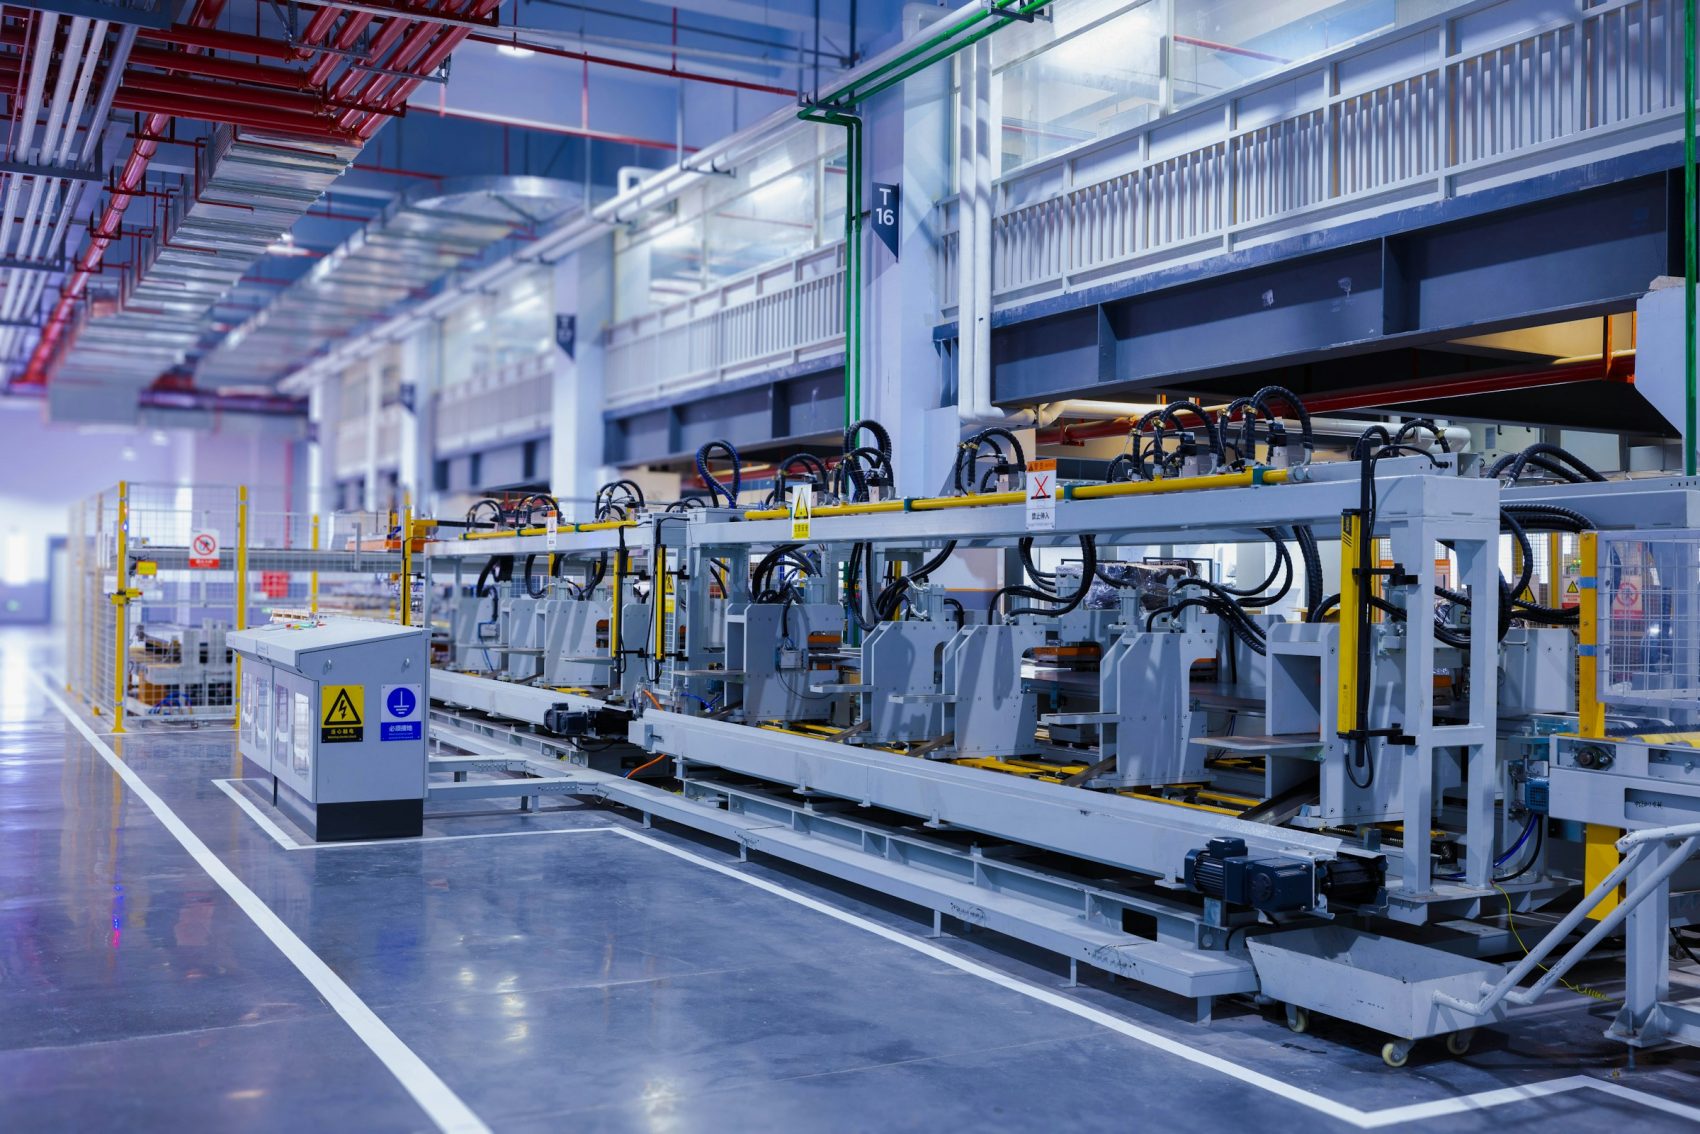
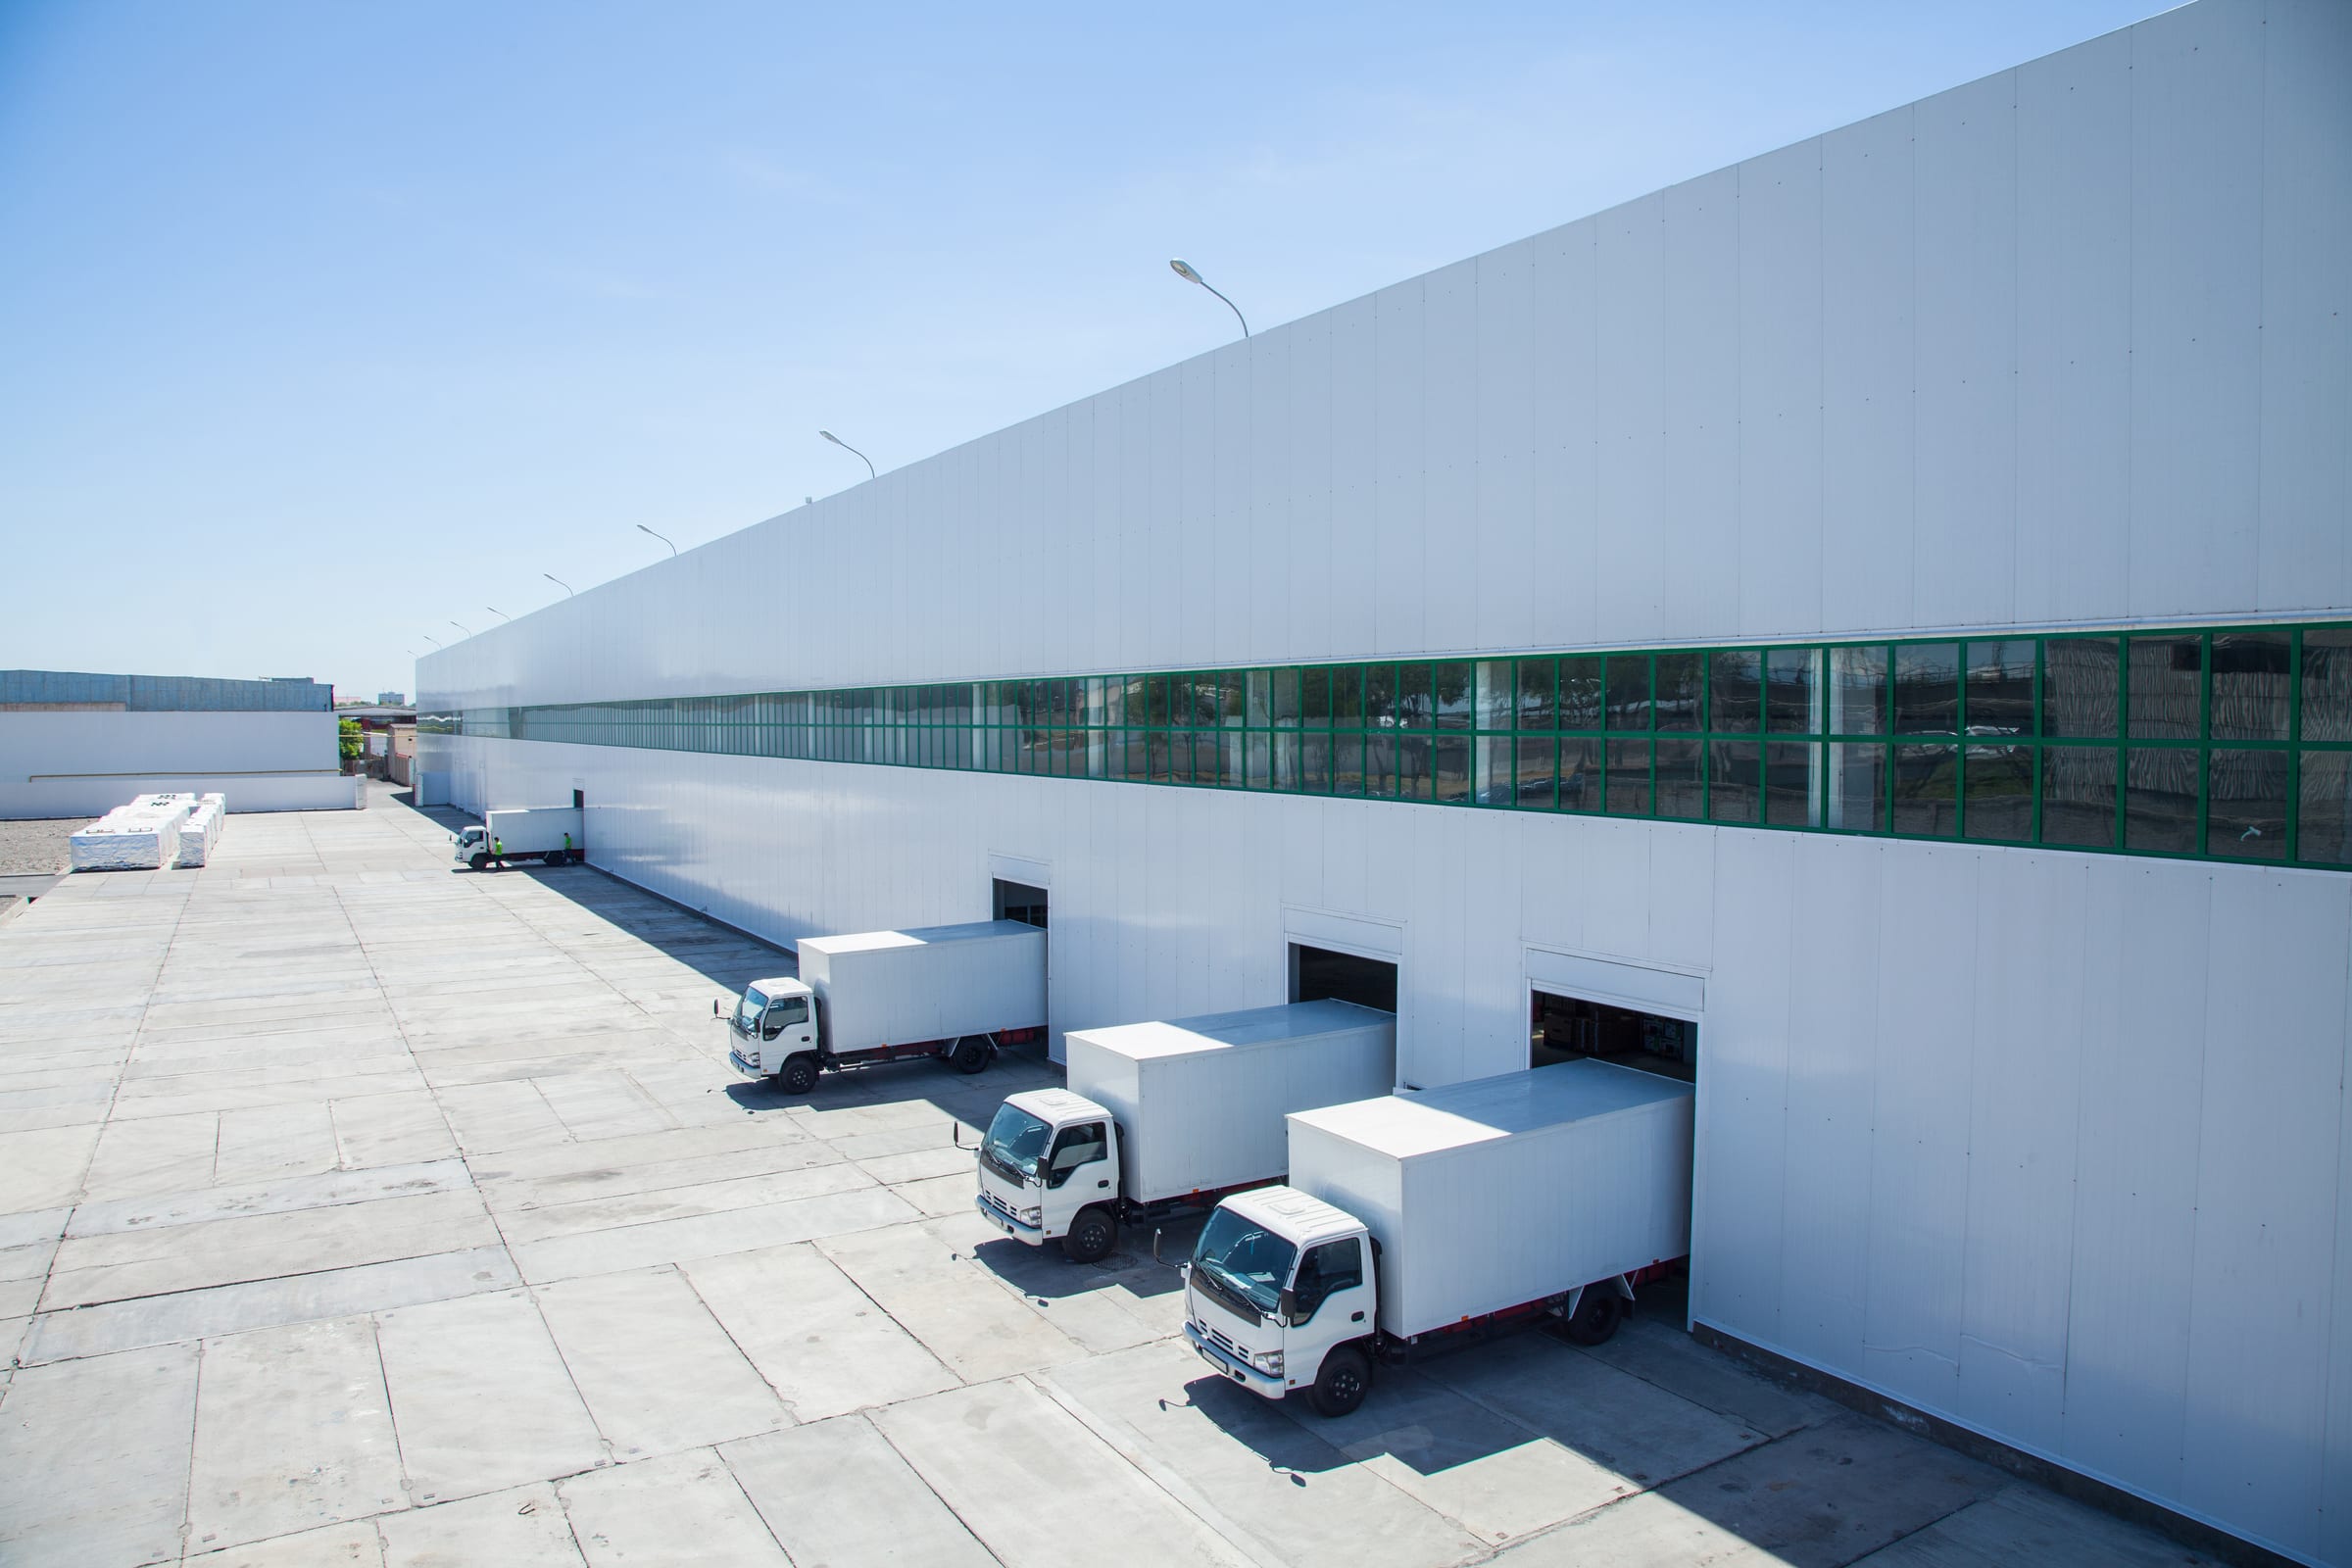
Underinsurance: why many warehouses would receive half of what their owner believes
The proportional rule is the clause that costs the most money in Spain and is almost never discovered until the day of the claim. How to detect it beforehand.
7 min read


